


Advertisement
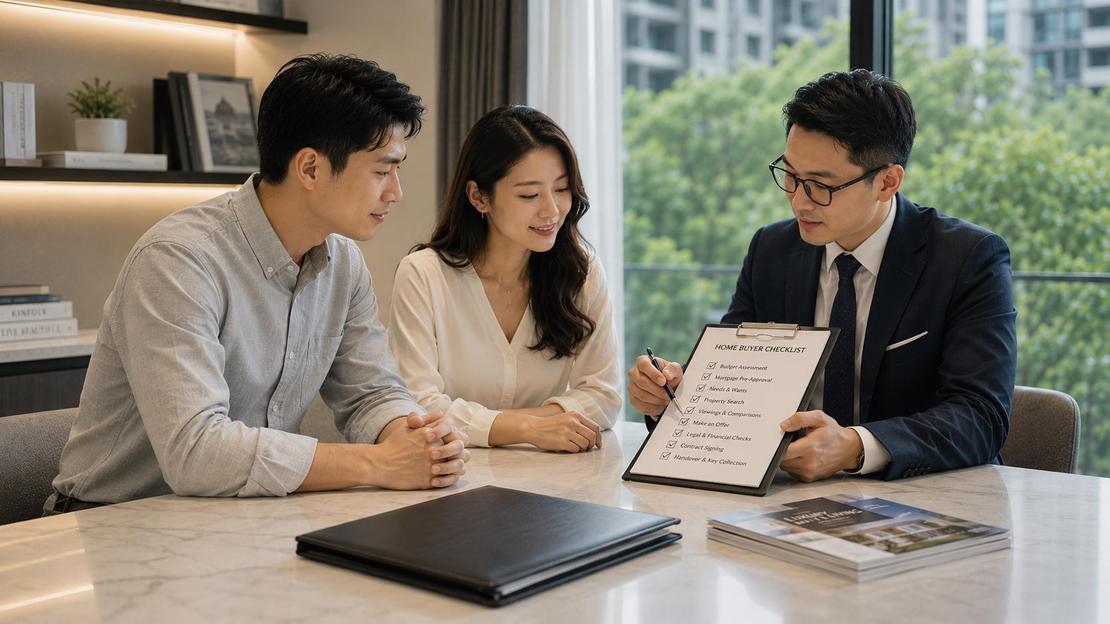
If you've recently started viewing properties or putting yours on the market, you may have noticed something a little different about the process. Your property agent is asking more questions than before — and for good reason. While it can feel like a lot of information to share, knowing what to expect makes the whole process much easier to navigate.
Why Is This Happening?
When you buy, sell, or rent a property, large sums of money change hands. This makes property transactions a target for money laundering and other financial crimes, where illicit funds can be disguised as legitimate property dealings. To protect all parties involved and uphold the integrity of Singapore's property market, the laws governing property agencies and agents' responsibilities were amended with effect from 1 July 2025.
Under the Estate Agents Act 2010 and the Estate Agents (Prevention of Money Laundering, Proliferation Financing and Terrorism Financing) Regulations 2021, property agents are now required to identify and verify the identity of all parties — buyers, sellers, landlords, and tenants — before any agreement to acquire or dispose of the property is signed.
Think of it the way banks verify your income before approving a home loan. It's the same principle: making sure everything is in order before a major financial commitment is made.
What to Expect During Your Transaction
1. Who You Are, and What You'll Need to Provide
Before any agreement is signed, your agent will need to collect and verify your personal details. Here's what you will typically need:
Full name (as per your NRIC or passport)
Date of birth and nationality
NRIC number or passport details
Occupation and employer
Depending on your transaction, agents may request additional supporting documents, such as proof of employment or documentation showing where your funds are coming from. To avoid unnecessary back-and-forth, prepare your NRIC or passport, basic employment details, and a general sense of how you're funding the purchase — whether through CPF, a bank loan, or cash savings — ahead of signing the final agreement.
2. Both Sides of the Deal Get Checked
Here's something many people don't realise: these checks cover both parties in the transaction, regardless of who has an agent. Not having representation doesn't mean skipping the process. If you are buying directly without your own agent, the seller's agent is still legally required to collect and verify your details. If each party has their own agent, each agent will conduct checks on their respective clients.
If you are not comfortable sharing personal details with an agent who doesn't represent you, you may wish to appoint your own agent so someone is looking out for your interests too.
3. Higher-Risk Transactions May Require Proof of Funds
For most standard transactions, verifying your identity and employment details is sufficient. But in some transactions which may be considered higher-risk, agents may need to ask further questions about your source of funds or wealth. This could mean explaining in broad terms whether you're using CPF savings, a bank loan, proceeds from a previous property sale, or investment income. Agents are not assessing your financial decisions — they are simply confirming that the funds being used for the transaction are legitimate.
If you are transacting under a company or trust, expect additional documentation on ownership structure and who ultimately controls the entity.
4. No Information Means No Transaction
This is the most important thing to understand: these checks aren't optional. If the required information is not provided, your agent is legally unable to proceed. In some cases, they may also feel required to file a report with the relevant authorities. The rules apply to buyers, sellers, landlords, and tenants alike.
One exception: if you are renting an HDB flat strictly for residential use, these checks don't apply to you. For everything else — buying, selling, or renting private property — the rules apply in full.
5. Your Information Is Protected
Sharing personal and financial details naturally raises the question: what happens to them? All information collected must be handled in accordance with Singapore's Personal Data Protection Act (PDPA). Your agent and their agency cannot use your data for anything beyond what is required for the transaction. Records are also required to be kept for a minimum of five years under the regulations.
If you have concerns about how your data is handled, you can ask your agent what information is being collected and why. A professional, registered agent should answer these clearly and without hesitation. You can also verify any agent's registration and transaction history on the CEA Public Register.
The Bottom Line
Yes, there are more steps now. But they exist to keep Singapore's property market safe and trustworthy for everyone involved. The checks are not about scrutinising you — they are to ensure every transaction is legitimate, which ultimately protects everyone, including you.
Prepare your documents early, work with a registered agent, and the process is more straightforward than it sounds. By understanding the new requirements, you can navigate your property transaction with confidence and peace of mind.
 Watch AD Unlock More
Advertisement


Advertisement


Advertisement


Advertisement